Bad Credit Car Loan Approval in League City, TX
What League City, TX dealerships really check beyond your credit score for bad-credit auto loan approval — income, down payment, vehicle age, and LTV.
Here's the myth worth busting: a bad credit score alone does not decide whether you drive home from a League City, TX dealership. Lenders evaluating a subprime auto application look at your full credit report, your income, your down payment, the vehicle itself, and your loan-to-value ratio — and a weak score can be offset by strength in those other areas. The approval decision is a composite, not a cutoff.
It means the rest of your application has to work harder — and most of those levers are things you can control before you ever sit down with a finance manager. Volkswagen of Clear Lake works with local and national lenders to offer financing options for all credit types, including competitive rates direct from the manufacturer and local Texas banks, which gives bad-credit buyers in League City, TX more than one underwriting path to try.
What do dealerships actually see when they pull your credit in 2026?
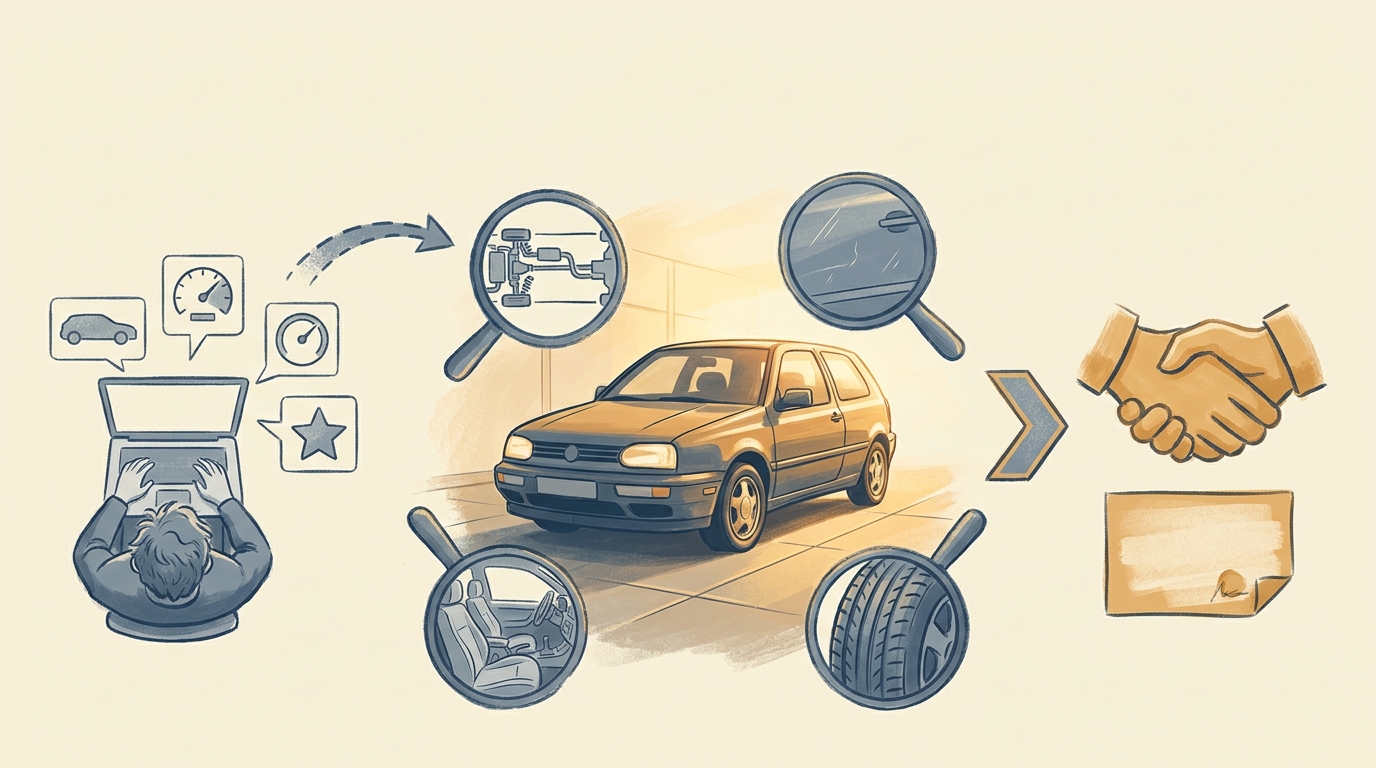
When a League City, TX dealership runs your credit, the finance office sees far more than a three-digit number. They see your credit score, payment history, current debts, past auto loans, recent credit inquiries, and any major negative items such as collections, bankruptcies, or repossessions. That full picture — not the score in isolation — shapes approval, interest rate, down payment requirements, and monthly payment structure.
Different lenders also use different scoring models. A lender will typically look at a FICO Auto Score before issuing a car loan, and FICO's industry-specific auto scores range from 250 to 900 — a wider band than the standard 300–850 consumer scale. That's why two lenders pulling the same report can quote different terms on the same day.
Why does income matter if it isn't part of your credit score?
Income is not part of a credit score calculation, but it is a separate line on the loan application that underwriters weigh heavily. Credit scores reflect only credit history — not income, job stability, or savings — because credit bureaus do not collect income data. Lenders ask for it directly, then compare the proposed payment against your existing obligations.
For subprime applications, income verification usually means recent pay stubs, W-2s, or bank statements for self-employed buyers. A stable income stream on a job you've held for a while gives the underwriter confidence that the payment is supportable, even if your score sits in a bruised range. According to Experian, credit history is typically more important to a lender than income because it shows a track record of managing debt — but on a thin or damaged file, verifiable income carries more of the decision.
How much does a down payment really change the approval odds?
A larger down payment lowers the amount financed, which lowers the loan-to-value ratio — one of the single biggest levers a bad-credit buyer in League City, TX can pull. LTV is commonly calculated as the amount financed divided by the vehicle's value; the lower that ratio, the less risk the lender takes on. Lower LTV means less lender risk, which often unlocks approvals that a zero-down application would not.
Down payments also absorb the first year of depreciation, protecting both you and the lender from going upside-down early in the loan. If you're trading in a vehicle you still owe money on, be careful: rolling negative equity into a new contract increases the new amount borrowed and can push the LTV ratio back up, undoing the benefit of your cash down.
Does the vehicle itself affect whether you get approved?
Yes — and this surprises most first-time subprime shoppers. The car's age, mileage, condition, and book value are part of the underwriting file because the vehicle is the collateral. Lenders cap how old or high-mileage a car they will finance for a given credit tier, and they also cap how far above book value they will lend.
That's why a newer vehicle with a clean value, like the 2026 Volkswagen Jetta, starting at $23,995 (as of October 2026) or the 2026 Volkswagen Taos, starting at $26,500 (as of October 2026), is often easier to finance on challenged credit than an older private-party car at a similar price. Certified pre-owned units with documented inspections and warranty coverage — Volkswagen's CPO program carries a CPO Warranty Deductible, $50 (as of September 2026) — give lenders further comfort because the collateral is a known quantity.
What approval factors can League City, TX buyers control before walking in?
Several. The score itself takes time to rebuild — payment history is among the most important factors in a credit score, and most negative information can stay on a credit report for seven years — but the non-score factors move quickly. Save for a down payment, document your income, pay down revolving balances to improve credit utilization, and avoid new credit applications in the weeks before you shop.
| Factor | What underwriters want to see | How quickly you can improve it |
|---|---|---|
| Credit report | No new lates, collections, or inquiries | Months |
| Income | Verifiable, stable, sufficient for payment + existing debt | Immediate (document what you have) |
| Down payment | Enough cash to bring LTV into lender's range | Weeks to months |
| Vehicle choice | Newer, lower-mileage, within book value | Immediate (choose at the dealership) |
| Trade-in equity | Positive equity, not rolled negative equity | Depends on current loan |
How does working with a franchise dealer differ from an online lender for subprime buyers?
A franchise dealer with multiple lender relationships can shop one application across several underwriting desks at once — manufacturer captive finance, national banks, and regional Texas banks — rather than forcing you to apply individually to each. For local buyers, that single-pull, multiple-decision approach often surfaces an approval path a single online lender would miss.
Volkswagen of Clear Lake, which has thrived under new ownership since 2026 as part of the Feel Good Automotive Group, works directly with Volkswagen Credit alongside national and local Texas lenders. Returning customers who purchase through Volkswagen Credit also have their disposition fee waived, and leasing another Volkswagen waives both the disposition fee and the security deposit — the kind of structural benefit a captive-plus-local lender mix can offer that a standalone online shop generally can't.
Arnold was so great. He was very helpful and got us where we wanted to pay monthly. Thank you for being super patient with us.
Frequently asked questions
What credit score is considered "bad" for a car loan?
There is no single universal cutoff, because different lenders use different scoring models. On the standard 300–850 FICO scale, scores below roughly 670 are generally treated as subprime, and FICO's industry-specific auto scores run on a wider 250–900 scale that your lender may use instead. Approval depends on the full application, not the number alone.
Can I get approved for a car loan with no credit history?
Yes, though the path differs from a bad-credit approval. With no credit file, lenders rely more heavily on verifiable income, length of employment, residence stability, down payment size, and a co-signer if available. A newer vehicle with a strong book value helps because the collateral is easier for the lender to price.
How much should I put down with bad credit?
Enough to bring the loan-to-value ratio into the lender's comfort range for your credit tier. There is no universal required amount, but a larger down payment lowers LTV, offsets first-year depreciation, and often unlocks approvals that a zero-down application would not. Cash down is usually more effective than rolled trade-in equity.
Will multiple dealerships pulling my credit hurt my score?
Auto loan inquiries made within a short shopping window are generally treated as a single inquiry by major scoring models, so comparison shopping does not stack damage the way unrelated hard pulls would. Recent credit inquiries are one factor lenders see on your report, but concentrated auto-loan shopping is designed into the scoring math.
Does a repossession or bankruptcy mean I can't finance a car?
No, but it narrows the lender pool and typically raises the down payment requirement. A credit reporting bureau can generally report most negative information for seven years, so the item stays visible for a while — but subprime lenders routinely approve buyers with these items on file when income, down payment, and vehicle choice support the application.
Is it better to get pre-approved before visiting a dealership?
Pre-approval gives you a baseline, but at a franchise dealership, the finance office can often shop your application across multiple lenders at once — including the manufacturer's captive and local Texas banks — which may surface terms a single pre-approval wouldn't. For bad-credit buyers, letting the dealer run the comparison alongside any pre-approval you already hold is usually the stronger play.
Where League City, TX buyers can go from here
If your score is bruised but your income is steady, you have cash for a down payment, and you're willing to be flexible on the vehicle, you have more approval paths than the one-number myth suggests. The job is to walk in with the controllable factors optimized and let a dealer with multiple lender relationships find the match. Readers in League City, TX who want this handled professionally can reach Volkswagen of Clear Lake at (832) 432-7969 or https://www.vwofclearlake.com/ to start the conversation.