Low Credit Auto Loan in League City, TX: How It Works
How car financing actually works for League City, TX buyers with low credit — what lenders weigh beyond your score, and how to improve approval odds.
Getting a car loan in League City, TX with a low credit score is possible because lenders weigh income, employment stability, debt-to-income ratio, and down payment alongside the score itself.
What counts as a low credit score when financing a car?
FICO scores run from 300 to 850. A score below 580 is rated Poor, 580–669 is Fair, and 670–739 is Good. Experian groups 501–600 as subprime and 300–500 as deep subprime — the two bands most lenders mean when they say "low credit." There is no single minimum credit score required by all lenders; each lender sets its own criteria.
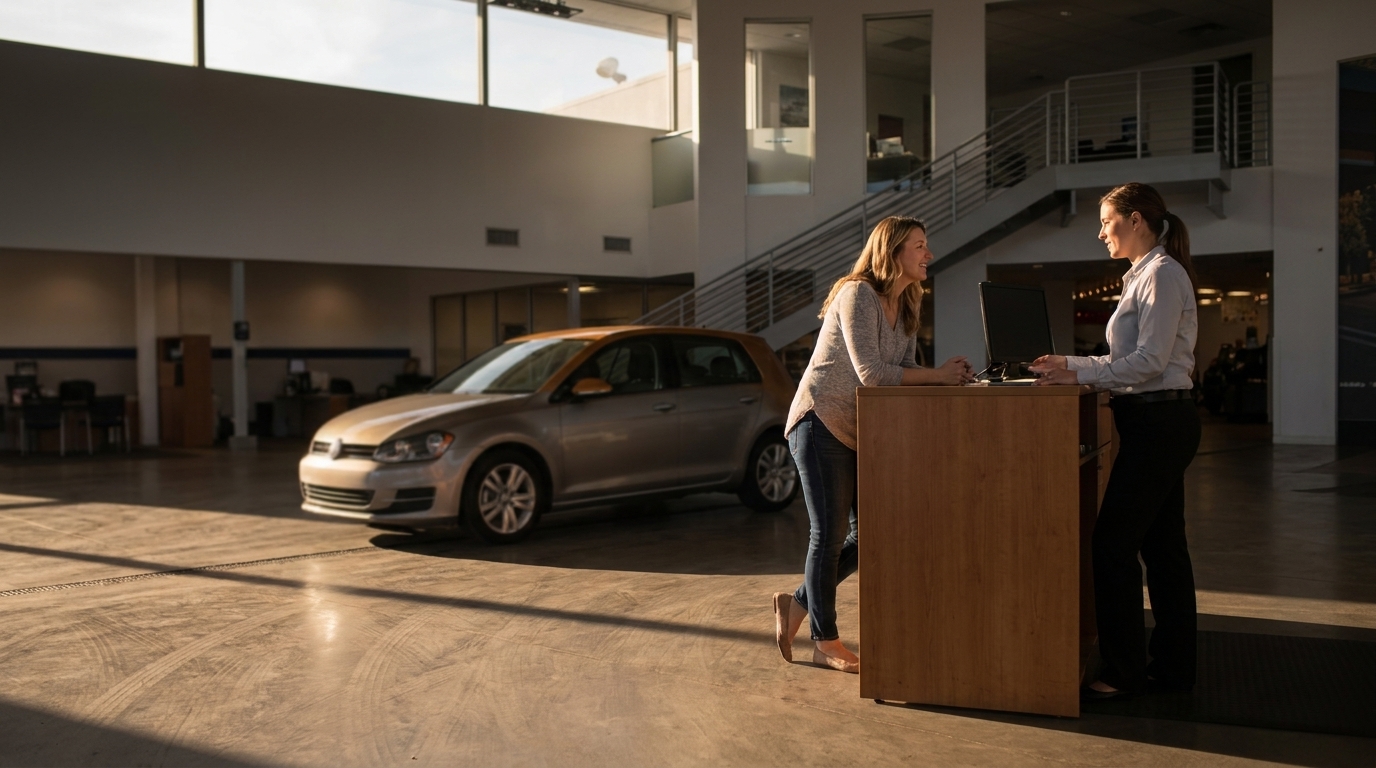
That last point matters in southeast Houston. Volkswagen of Clear Lake, located at 3310 Gulf Freeway in League City, works with local and national lenders to offer financing options for all credit types, including competitive rates direct from the manufacturer and local Texas banks. One lender's decline is not the market's decline.
How do subprime auto lenders actually decide?
Subprime lenders look past the score to four pillars: verifiable income, employment stability, debt-to-income ratio, and down payment size. Loan length and whether the vehicle is new or used also move the rate. The score sets the starting point; the rest of the file decides whether you get approved and on what terms.
Debt-to-income ratio is calculated by dividing total monthly debt payments by gross monthly income before taxes. The lower the DTI, the less risky the applicant looks. A buyer with a 560 FICO and a 25% DTI, steady two-year job history, and $3,000 down often beats a 620 applicant with maxed cards and nothing down.
What vehicles qualify for a subprime auto loan?
Subprime lenders commonly require the financed vehicle to be less than 10 years old (some cap it at seven), have no more than 100,000 miles, and meet a minimum financing amount — according to thecarconnection.com, commonly at least $5,000. Bad-credit borrowers also tend to have better luck on used vehicles because the smaller loan amount lowers the lender's exposure.
| Factor | Common subprime requirement |
|---|---|
| Vehicle age | Less than 10 years (some lenders: less than 7) |
| Mileage | No more than 100,000 miles |
| Minimum financed amount | At least $5,000 (per thecarconnection.com) |
| Credit band — subprime | FICO 501–600 (Experian) |
| Credit band — deep subprime | FICO 300–500 (Experian) |
What rates should League City, TX subprime buyers expect?
These are national historical averages, not quotes — your actual rate depends on the lender, the vehicle, and the full application.
Lender type matters too. Translation: where the loan is placed changes both the price and the risk of the deal going sideways.
How does a down payment change the outcome?
A larger down payment reduces the balance financed, which can lower monthly payments and help secure more favorable terms. It also shrinks the lender's loss exposure, which is exactly what a subprime underwriter is pricing against. For a Gulf Coast buyer financing a used SUV, moving from $500 down to $2,500 down can shift the file from "maybe" to "approved," and often knocks points off the rate.
Factor in Texas's 6.25% motor-vehicle sales tax (confirm the current figure and any title and registration charges with the Texas Comptroller or your dealer at purchase) when sizing your cash to close. Rolling tax and fees into the loan is possible but inflates the amount financed and the interest you pay over the term.
How should you shop lenders without wrecking your score?
Shop multiple lenders inside a tight window. Many credit-scoring models treat multiple auto-loan inquiries as a single inquiry when they occur within a roughly 14–45-day window; the exact treatment depends on the scoring model. Submitting applications across two or three weeks therefore costs you one inquiry, not five.
A dealer finance office that already works with multiple lenders can do this shopping in one sitting. Volkswagen of Clear Lake routes applications to both manufacturer financing and local Texas banks, which lets a single credit pull reach several underwriters. Returning customers who purchase through Volkswagen Credit at Volkswagen of Clear Lake also have their disposition fee waived, and leasing another Volkswagen waives both the disposition fee and the security deposit.
What does the process look like at a franchise dealer?
Bring pay stubs (typically two most recent), proof of residence, a valid Texas driver's license, insurance information, and any references the lender requests. Know your realistic monthly payment ceiling before you walk in — not the maximum a lender will approve. For used inventory, confirm the vehicle meets the lender's age and mileage caps before you fall in love with it.
"Thank you Arnold for thoroughly explaining what my options were coming out of my lease into a purchase. I’m very thankful that Arnold was very patient and understanding of my needs. Love my 2024 Crossport" — 5★ · Erika, Dec 2024
Frequently asked questions
Can I get approved for a car loan in League City, TX with a 550 credit score?
Yes, approval at 550 is realistic through subprime lenders, though the rate will be higher. Approval odds improve with verifiable income, a low debt-to-income ratio, and a down payment of several thousand dollars.
How much should I put down with bad credit?
Put down as much as you reasonably can — a larger down payment reduces the balance financed, lowers monthly payments, and helps secure more favorable terms. Many subprime lenders expect meaningful cash down on used vehicles. Combine the down payment with cash for Texas's 6.25% motor-vehicle sales tax and title and registration charges so those costs don't inflate the loan.
Will applying at several lenders hurt my credit score?
Not materially, if you cluster the applications. Many credit-scoring models treat multiple auto-loan inquiries as a single inquiry when they occur within a roughly 14–45-day window. The exact treatment depends on the scoring model, but concentrating your shopping into two or three weeks is the standard way to compare offers without stacking hard pulls.
What vehicles can I finance with a subprime auto loan?
Subprime lenders commonly require the vehicle to be less than 10 years old (some cap it at seven), have no more than 100,000 miles, and meet a minimum financing amount of at least $5,000 per thecarconnection.com. Bad-credit borrowers also tend to qualify more easily on used vehicles because the smaller loan amount reduces the lender's risk exposure.
Does income or credit score matter more for approval?
Both matter, but income, employment stability, and debt-to-income ratio can offset a weak score. Lenders also weigh loan length, down payment size, and whether the vehicle is new or used. A verifiable income with a low DTI and a solid down payment often approves where a thin or inconsistent file at the same score would not.
Is it better to buy new or used with low credit?
Used usually wins for subprime buyers because the lower selling price shrinks the loan amount and the lender's exposure.
The bottom line for League City, TX buyers
A low credit score raises the price of the loan — it rarely closes the door. The levers that move approval are the ones you control before you apply: a stronger down payment, a lower DTI, documented income, and a realistic vehicle choice that fits subprime age, mileage, and loan-size rules. Shop your financing inside a two-to-three-week window and let one credit pull reach multiple lenders.
Readers in League City, TX who want this handled professionally can reach Volkswagen of Clear Lake at (832) 432-7969 or https://www.vwofclearlake.com/ to walk through options with a finance team that works with lenders across the credit spectrum.